How to do inventory in hospitality: count 25 products, not 250, and find the waste you don't see
By Samuel Carrillo9 min read
Published 13 October 2026.
You ordered less for three months and food cost didn't move
Your food cost sat at 46% and you had an explanation: a full cooler.
You were over-ordering, cash sat in boxes, and that inflated the number. So you started ordering tight.
Three months later, the number was still there.
It's a client of ours, and the belief was reasonable. The problem was they had never checked it, because they had never counted.
There's no point closing the month if you don't know how much money is in your cooler.
One warning before we go on: counting doesn't lower food cost. It tells you what it is, and it's almost always worse than you thought.
What should be left in the cooler has a name: theoretical inventory
Real monthly food cost doesn't come from what you buy. It comes from what you consume.
Month's consumption = opening stock + purchases − closing stock.
Purchases come from delivery notes. What's left you only know by counting.
Theoretical inventory is what should be in storage if everything that left was sold to recipe: what you had, plus what you bought, minus sales times the grams in each recipe costing.
If the dishes that use a reference aren't costed, that reference has no theoretical. That's why it helps to understand first why a dish costs one thing on the sheet and another in your kitchen.
How to do inventory in hospitality, step by step
Four steps: euro-ranked list, count on the last day, value at the latest delivery note, and compare with theoretical.
01 Choose what to count by euros, not by kilos
You don't count everything. You count what weighs in money.
In most stores, 20% of references make up about 80% of value. That's Pareto: a practical rule, not a law.
To build your list, take the last three months of delivery notes and rank references by euros spent. The top 20 or 30 are your inventory.
The trap is choosing by volume. Twenty kilos of potato fill half the cooler and are worth less than two pieces of Iberian ham. Potato stays out; ham stays in.
When I ran purchasing for eight sites, I set the count list. That way it doesn't change with whoever is counting.
02 Count on the last day of the month, always at the same time
Before opening or after closing, never mid-service. And at the same time each month so the two counts are comparable.
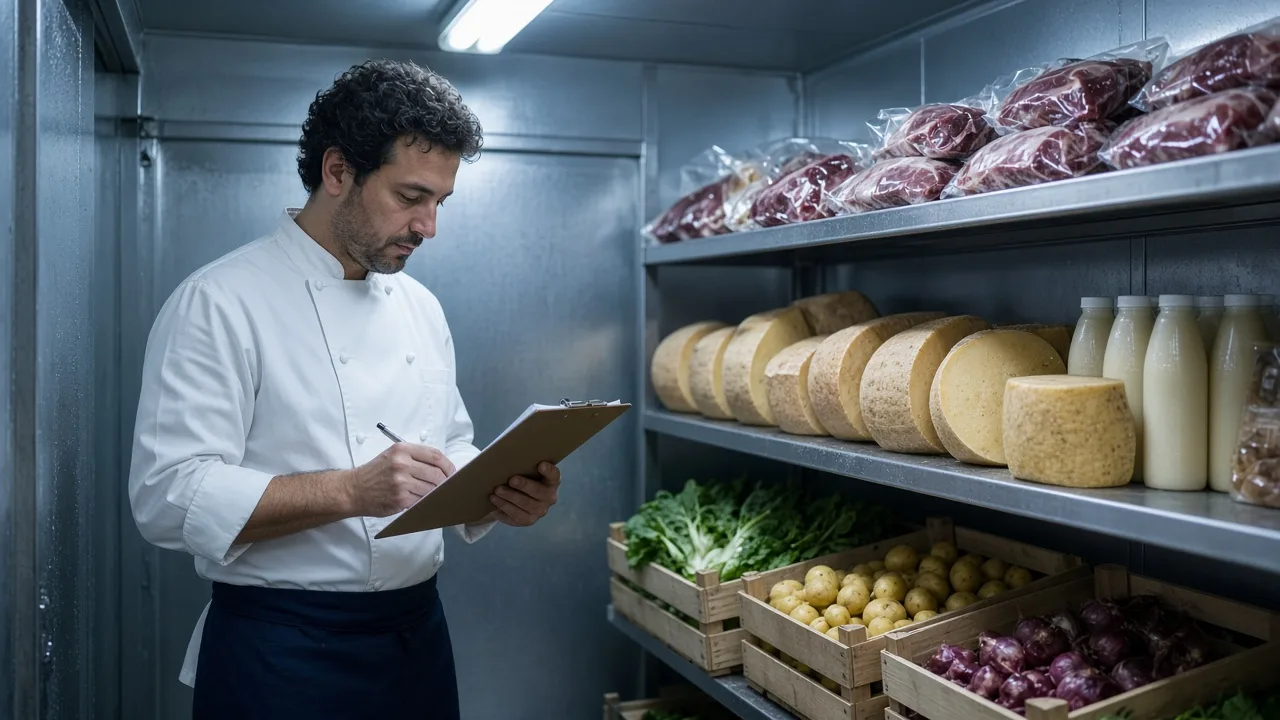
Count open items too: the started bottle, the cut cheese, the cooler mise en place. Each prep is valued with its own recipe costing.
The costliest trap is the missing delivery note. If the order arrived on the 31st and is in the cooler, its note must be in this month's purchases.
If it isn't, you count as stock something that isn't in purchases, and the month's food cost comes out lower than it is.
03 What price do I value stock at?
Units counted times the latest delivery-note price, ex-VAT. Always the same rule.
Valuing at the price you remember is valuing at the price from six months ago.
Latest delivery-note price is close to FIFO, which assumes first in is first out. The Spanish General Accounting Plan sets weighted average as the general method, but adds that "the FIFO method is acceptable and may be adopted if the company considers it more convenient for its management".
To close your month, that's enough.
04 Compare: the gap is what left without being sold
Put side by side, reference by reference, what should be there and what you counted.
The euro gap is what left your store without going through the till.
Not all of it is waste. That includes expired product and poor portioning, but also comps, staff meals not logged, and gram weights nobody respects on the pass.
Before looking for culprits, review the recipe costings for dishes that use that reference. It's the first fix and the cheapest one.
How often should a restaurant take inventory?
Once a month, on the last day. That's the cadence that gives you a real monthly food cost and that you can sustain.
The first month compares nothing. It only gives you the starting point: opening stock for month two.
In between, unscheduled audits: five references from the list, mid-month, without notice. That's what I did, and it shows whether the theoretical holds before month-end.
If your site is small, the method doesn't change. The list does: with 10 or 15 references you probably cover most of the value, and the count fits before opening.
From 46% to 42%, and not to 35%
Back to the client at the start.
They expected that, after stripping out what sat in the cooler, food cost would fall to 35%. They closed their first inventory month and it didn't drop below 42%.
Stock explained four points at most. The other seven weren't in the cooler: they had gone as waste.
The euro figures are illustrative: we assume €30,000 monthly sales ex-VAT. The food-cost percentages are the client's; the sales figure and euro conversion are not. This is not a measured theoretical-vs-physical variance line by line.
At that sales level, 46% was €13,800 in purchases and the real 42%, €12,600.
What sat in the cooler was €1,200. What left as waste, at least €2,100 a month.
That's more than €25,000 a year that wasn't in any till. Ordering less was never going to get it back.
Idle stock (≈ 4 pts)
€1,200
Waste per month
≥ €2,100
Uncollected per year
> €25,000
Illustration with assumed sales: 4 pts of idle stock and 7 pts to the hoped-for 35% ≈ €1,200 and €2,100.
What 25 products don't tell you
The 20% of value left off the list you don't control. If a cheap reference starts disappearing, you won't see it until you add it to the list.
And three things not to take as gospel:
- The 80/20 varies with the menu. With many expensive products, the list gets longer. Review it each quarter with delivery notes.
- Latest delivery-note price is for managing. It doesn't have to be how your accountant values stock at 31 December. They close that.
- Theoretical is only as good as your recipe costings. If the sheet grams aren't what leave the pass, part of the gap is the costing, not the waste.
The case is one client. Your gap may be larger or smaller, but you won't know it without counting.
If you've never closed a month by counting and don't know which references to start with, tell us: with your delivery notes, recipe costings and POS extract we help you build the theoretical and lock in the 20 or 30 references to count.
On the 31st you count. On the 1st you already know how much money is in the cooler.
Never closed a month by counting?
Tell us how you run it today: with your delivery notes, recipe costings and POS extract we help you build the theoretical and lock in the 20 or 30 references to count.
From Tipi we help you see waste in euros, not only as a percentage.
Sources
- Royal Decree 1514/2007 of 16 November approving the Spanish General Accounting Plan, measurement basis 10, inventories.
- Client case: Tipi advisory, told anonymously. Food-cost percentages are the client's.
- Count method, assumed sales and euro conversion: Tipi's own work.